
Homeowners Insurance Florida – Top Five Policy Exclusions
Every Florida homeowners policy leaves certain losses out, and we would rather you see them now than at claim time. Here are the five exclusions we walk through with you, and the coverage we can add for each.
Editor’s note: originally published in 2013; reviewed and updated in 2026 for current Florida flood-insurance pricing and policy limits.
When it comes to home insurance many people think their policy covers everything. Many homeowners discover only at claim time that a loss is not covered until after the fact. This can be a costly mistake. Understanding Florida homeowners insurance exclusions is essential for every Florida homeowner. Knowing what your policy does not cover can save you thousands of dollars and prevent unpleasant surprises when filing a claim. These are the top 5 Florida homeowners insurance exclusions that people often overlook.5. Theft or loss of jewelry, firearms, antiques and other items of intrinsic value
. This often comes as a big shock when someone calls to report the loss of an expensive diamond ring, only to find out there is a special limit, commonly $1,000-$2,500 depending on the form (check your policy), and zero coverage for accidental misplacement. The key thing to remember here is if you own expensive jewelry ask your agent to schedule the items you cannot afford to lose, or better yet, buy a personal article floater policy, which is a separate policy just for those items you want to insure for loss.
4. Motor vehicles
Most homeowners forms limit liability for motorized vehicles: a golf cart may be covered only on a golf course or, on newer forms, inside the private community where you live where carts are permitted, a mower or ATV only while it is used to service the residence, and a motorized scooter usually falls under the motor vehicle exclusion, so check your form and carry a separate policy for anything used beyond those places. The exclusion does not apply in a few circumstances, like using a four wheeler around ones home for hauling trash or yard debris, and those motorized vehicles designed for assisting the handicapped.3. Building defects
Say your builder uses cheap materials that end up failing later, or say the builder actually forgot to use certain items in the construction process and you later suffer a loss as a direct result of this defective construction, do not count on your home insurance policy to bail you out. There is an exclusion in your home insurance policy that excludes coverage for any faulty, inadequate or defective items. It is a broad exclusion including defects of planning, zoning, development, surveying, design, renovation materials, maintenance and more. Folks who had Chinese drywall put in their homes found out the hard way that this exclusion meant their homeowners policy did not include coverage to remediate the damage from the defective drywall. This is why it is so important to hire reputable builders and contractors who will be there to stand behind their products and work.2. Rising water
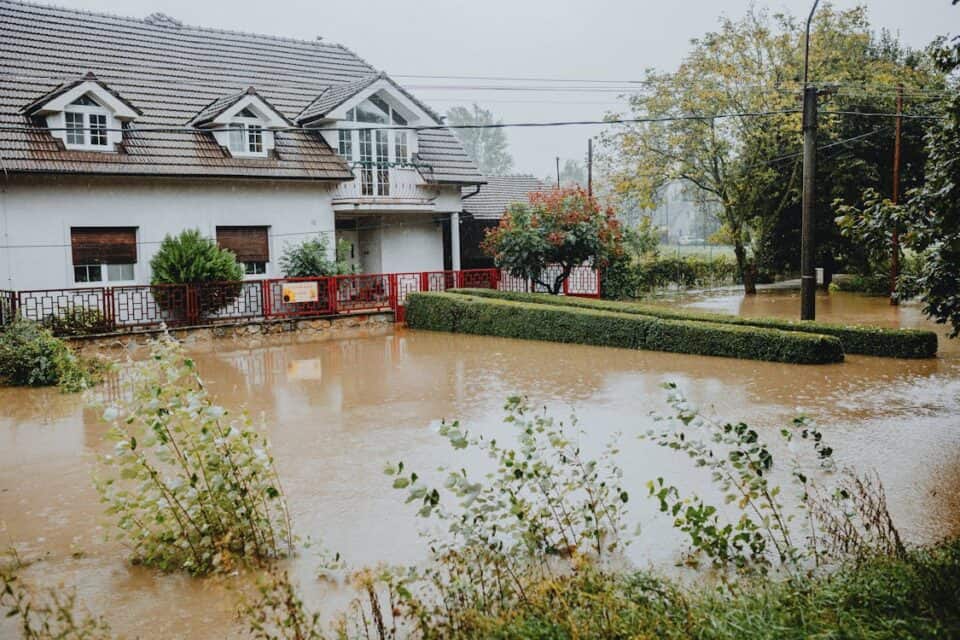
The only way to cover your home and property from rising water-even from heavy rain- is to purchase a flood policy. Many times people think of a flooding event as a tidal wave of water that couldn’t possibly happen to them. However, many flooding claims are from rising water due to heavy rains that inundate two or more properties or two or more acres of normally dry land. Since FEMA moved the NFIP to Risk Rating 2.0, every property is priced individually on its own flood risk — as an independent agency we compare NFIP and private flood options. Rising water is insured through flood coverage, and it comes three ways: an NFIP policy, a private flood policy, or a flood endorsement some homeowners carriers add to their own forms, and the question for every Florida home is how much to carry.1. Water damage over time
This is probably the biggest gotcha in the policy. Home insurance policies are generally written to cover sudden and accidental water damage. An example would be a pipe breaking or a dishwasher or washing machine that overflows. Many carriers now limit water losses further: a dollar sublimit on water claims, exclusions for leaks that ran past a stated number of days, limits tied to the age of the home or water heater, and a lower sublimit unless the carrier’s repair program is used, so read the water provisions of your own policy with your agent. The problem is far too many people make claims for deferred maintenance like small roof leaks that build over time or small tile cracks in the shower that are never caulked. The best thing a homeowner can do is once or twice a year go through and caulk all windows and bath fixtures and pop your head up in the attic with a flashlight and look for small leaks that could rot entire sections of your roof over time. Be sure to beware of roofing scams when hiring contractors for repairs.Understanding what you are not covered for is as important as knowing what you are covered for. Being aware of these Florida homeowners insurance exclusions helps you make smarter decisions about additional coverage. If you have a specific coverage question, the best thing to do is contact your agent and ask. You should also learn about flood insurance options to cover the one big gap every home policy leaves. A little prevention and education will go a long way to keeping your family and property protected.
Policy Exclusions FAQ
Is my jewelry covered under a Florida homeowners policy?
Only up to a special theft limit, commonly $1,000 to $2,500 depending on the policy form, and accidental loss is usually not covered at all. Scheduling the items or adding a personal articles floater is how you insure pieces you cannot afford to lose.
Are golf carts and four-wheelers covered by home insurance?
Liability for motorized vehicles used away from the premises is generally excluded. Limited exceptions exist for vehicles used to service the property or to assist a disabled person. An inexpensive stand-alone policy or endorsement covers the rest.
Does homeowners insurance pay for construction defects?
No. Policies exclude losses caused by faulty, inadequate or defective materials, design, workmanship and maintenance. The Chinese-drywall episode is the classic Florida example of that exclusion at work.
Does my home policy cover rain-driven flooding?
Rising water, including heavy rain that pools and enters the home, is excluded from homeowners policies. Flood coverage comes three ways, an NFIP policy, a private flood policy, or a flood endorsement some homeowners carriers add to their own forms, and the question is how much to carry.
What kind of water damage is excluded?
Damage that develops over time, such as a slow roof leak or a shower that was never re-caulked, is treated as maintenance and excluded. Sudden and accidental events, such as a burst pipe, are the kind of water loss policies are written to address.